Best-Arm Identification with High-Dimensional Covariates
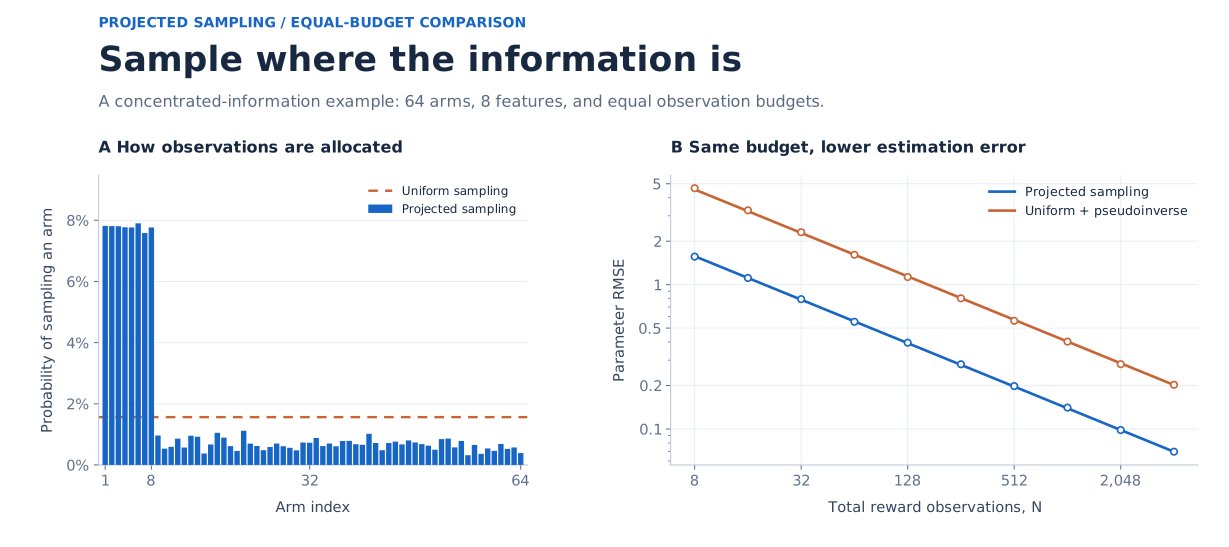
Projected sampling probabilities and parameter estimation error under the same observation budget.
Developed an unbiased estimator using left singular vectors and an L1-norm-based randomized sampling mechanism to reconstruct high-dimensional signals from a single coordinate observation per decision step.
Proved unbiasedness and covariance preservation and extended spectral analysis to feature selection using high-order perturbation analysis and the Sherman-Morrison formula.
Implemented numerical experiments on SVD-constructed instances, confirming that empirical convergence rates align with the theoretical sample complexity and regret guarantees.